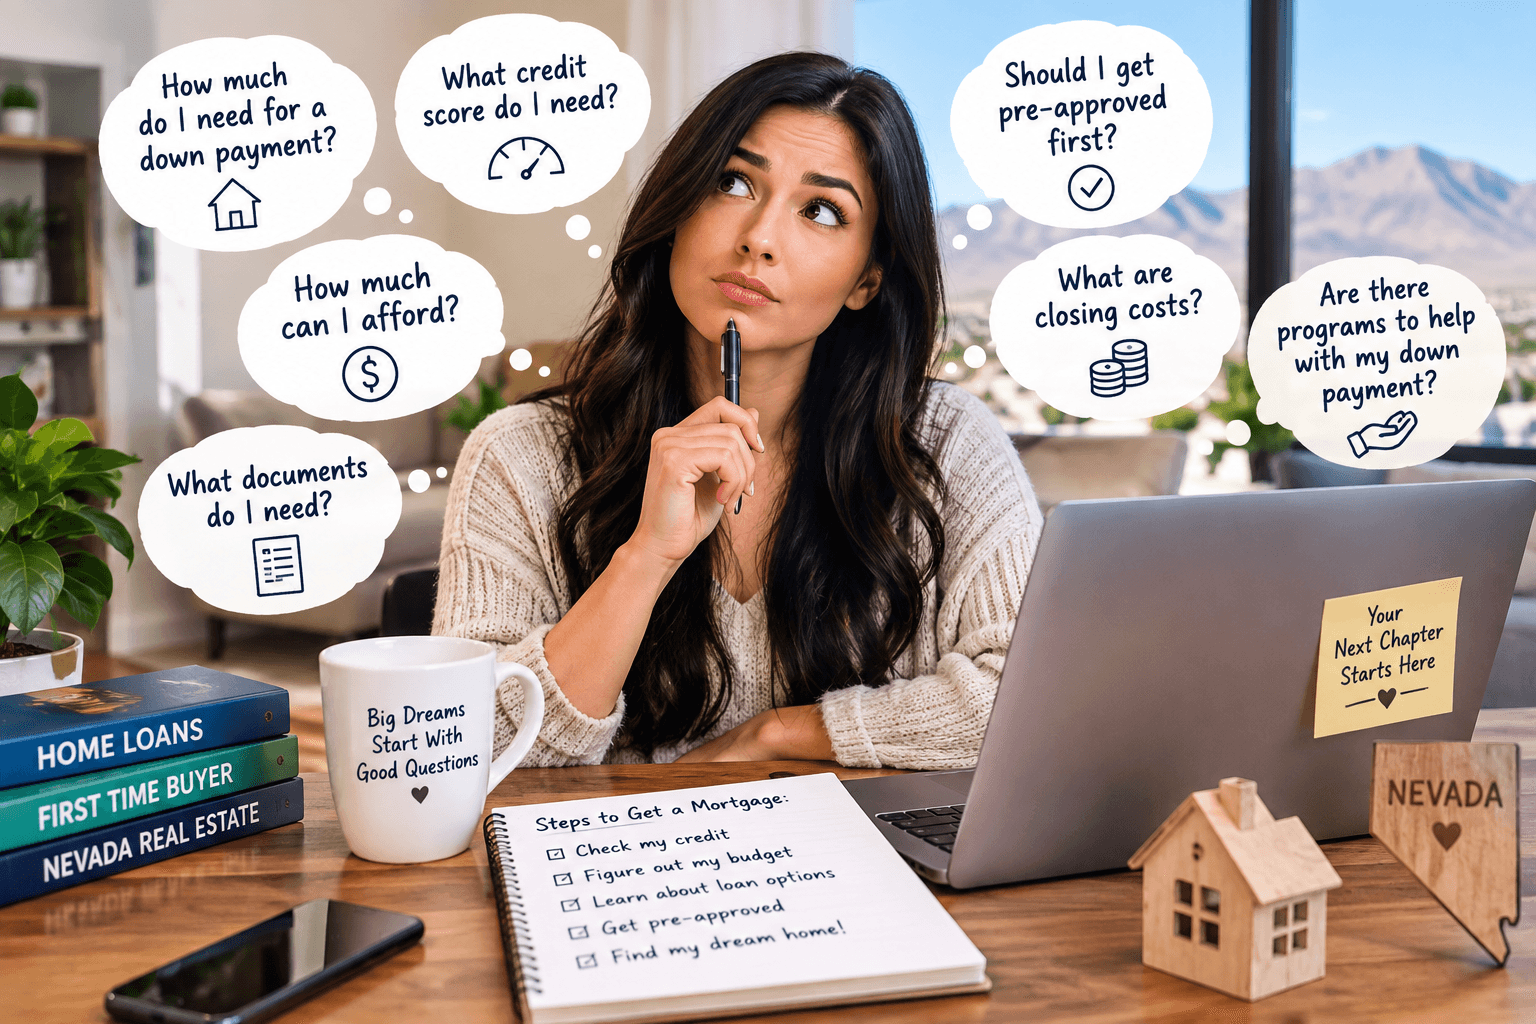
It depends on the type of mortgage you choose.
You do not necessarily need 20% down to buy a home.
Depending on your situation, there may be conventional, FHA, VA, USDA, or other financing options with different down-payment requirements.
For example, FHA financing can require as little as 3.5% down in many cases, subject to the program's requirements.
There may also be assistance programs available to eligible Nevada buyers.
The important question isn't simply, "How much should I put down?" It's "Which loan option makes sense for my situation?"
There isn't one universal credit score that every borrower needs.
Your credit profile can affect both your ability to qualify and the interest rate and terms you may receive. Lenders can also consider your income, debts, assets, and other financial information.
Some loan programs are designed to accommodate borrowers with lower credit scores than others.
Don't automatically assume that your credit score means you can't buy a home.
This is one of the most important questions to answer before you start house hunting.
A lender looks at factors such as:
But there's an important difference between what a lender says you can qualify for and what you personally feel comfortable paying every month.
Your mortgage payment should fit into your overall household budget—not just the maximum amount a lender may approve.
A pre-approval is a lender's statement that they are tentatively willing to lend you up to a certain amount, based on information they review about your finances.
It can help you understand your potential buying range and show sellers that you're a serious buyer. However, a pre-approval is not a guaranteed final loan approval.
It can help you:
✅ Understand your potential budget
✅ Identify potential issues early
✅ Know what type of financing may fit
✅ Make your offer more credible to a seller
Tip: Consider getting pre-approved before seriously shopping for homes.
Your lender will typically need documentation to verify your financial situation.
Depending on your circumstances, this can include:
The exact documentation varies by borrower and loan program.
Don't worry if you don't have everything ready on day one. Your loan officer can tell you what is needed and when.
Closing costs are expenses associated with getting your mortgage and completing the home purchase.
They can include things such as:
The exact amount varies based on the transaction and loan.
Don't confuse closing costs with your down payment. They are separate parts of the money you may need to bring to closing.
No—not necessarily.
The 20% figure is commonly discussed because putting less than 20% down on many conventional loans can result in private mortgage insurance (PMI).
But there are many mortgage options with different down-payment requirements.
For example, FHA loans can allow a lower down payment for eligible borrowers, while VA loans may offer eligible veterans and service members financing options that don't require a down payment. Requirements and eligibility apply.
The right down payment depends on your loan program and financial goals.
PMI stands for Private Mortgage Insurance.
With many conventional mortgages, PMI may be required when your down payment is less than 20%.
PMI is designed to protect the lender—not the homeowner.
The amount and rules can vary depending on the loan and borrower.
That's why it's important to look at the total monthly payment, rather than focusing only on the interest rate.
When you formally apply for a mortgage, the lender generally obtains your credit report, which can result in a hard inquiry.
However, shopping for a mortgage does not mean every mortgage inquiry will necessarily count separately. The CFPB explains that multiple mortgage credit checks made within a 45-day window are generally treated as a single inquiry for scoring purposes.
That means you can shop around and compare mortgage options without assuming that every lender inquiry will independently damage your credit score.
Possibly.
Having less-than-perfect credit doesn't automatically mean you can't qualify for a mortgage.
Different loan programs have different requirements, and lenders consider more than just your credit score.
Your income, debts, credit history, assets, down payment, and other factors can all matter.
The best way to know what options may be available is to have your situation reviewed by a mortgage professional.
These terms can mean different things depending on the lender.
Generally, pre-qualification may involve an initial estimate based on information you provide, while pre-approval typically involves a more detailed review of your financial information.
The CFPB notes that lenders don't all use these terms in exactly the same way.
The important thing is to ask your lender what they actually reviewed and what the pre-approval is based on.
Yes, it's worth comparing your options.
Mortgage rates, fees, loan programs, and other terms can vary between lenders.
The CFPB recommends comparing multiple loan offers so you can look at the complete cost and terms—not just the advertised interest rate.
When comparing lenders, look at:
The lowest advertised rate isn't necessarily the lowest overall cost.
Once you're pre-approved, you can begin shopping for a home within your approved range.
After you find a home and your offer is accepted, the lender moves forward with the formal loan process.
This can include:
Application → Documentation → Processing → Underwriting → Appraisal/Property Review → Final Approval → Closing
Your lender will tell you what documents and actions are needed along the way.
Before closing, you'll receive a Closing Disclosure showing important final loan terms and closing costs. Federal rules generally require you to receive it at least three business days before closing.
Getting a mortgage doesn't have to feel confusing.
The first step is simply understanding where you stand and what options may be available to you.
Whether you're a:
-First-time homebuyer
- Veteran or active-duty service member
-Buyer looking for down-payment assistance
-Self-employed borrower
-Move-up buyer
-Investor
-Family looking for their next home
There may be different financing options worth exploring.
Don't wait until you've found your dream home to start asking questions.
Reach out today to discuss your goals, review your options, and take the first step toward getting home financing.
Mortgage programs, rates, fees, and qualification requirements can change. Your actual loan terms and eligibility will depend on your individual circumstances, the selected loan program, lender requirements, and applicable guidelines.