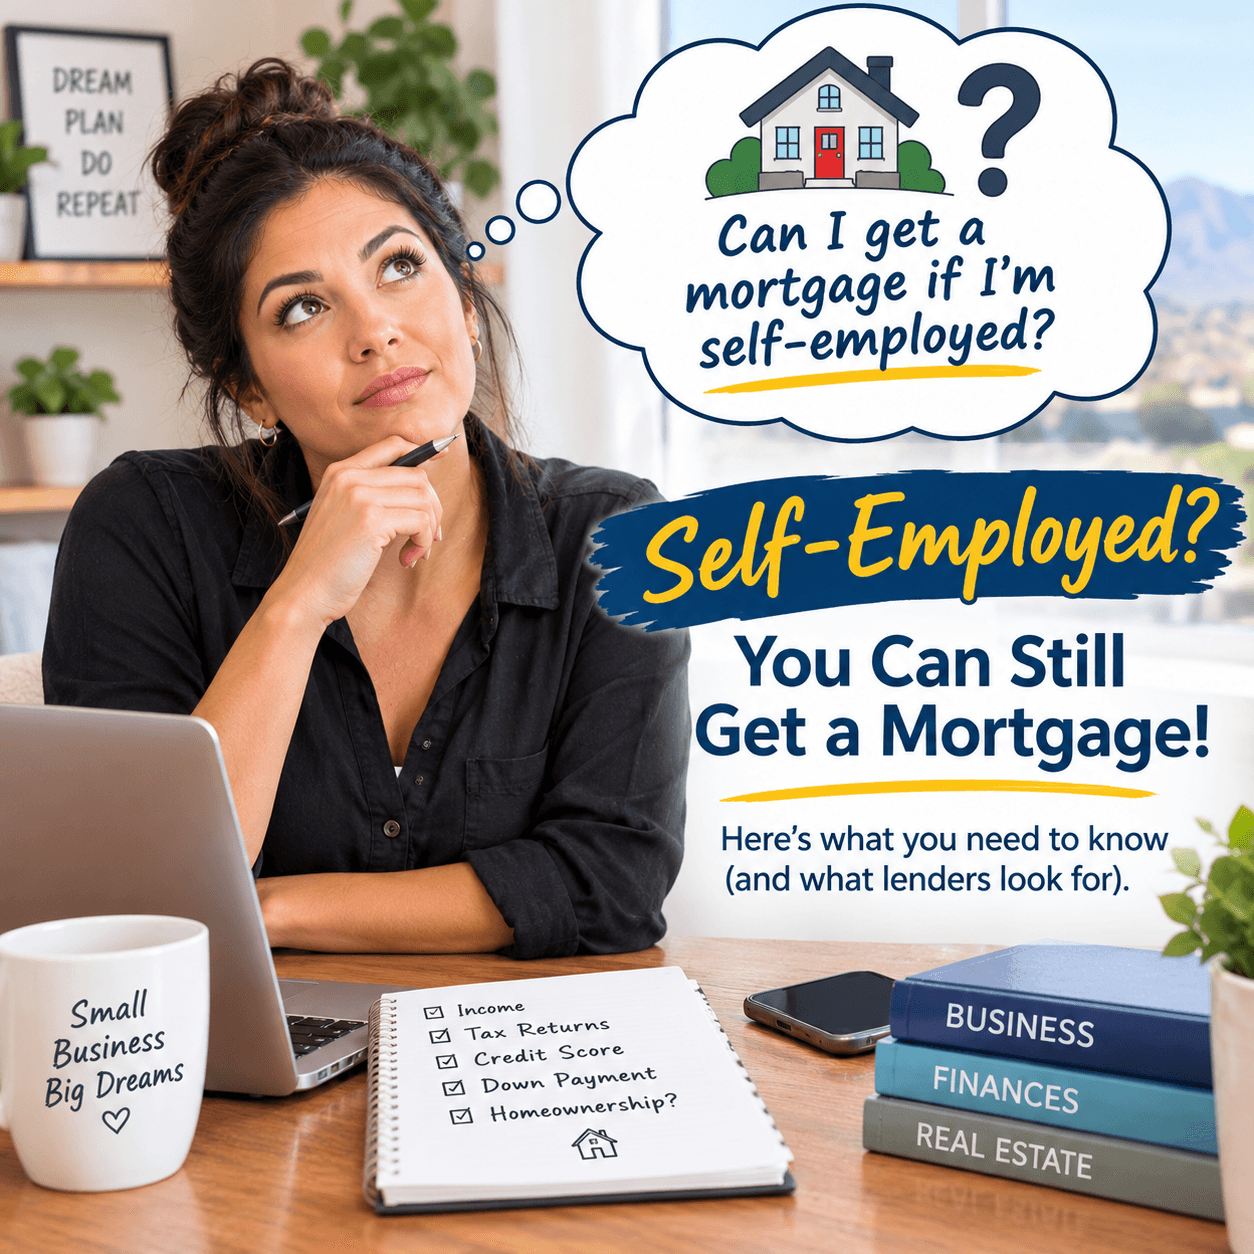
When it comes to securing a mortgage, self-employed individuals often face unique challenges that can make the process feel overwhelming. Unlike traditional employees who receive a steady paycheck, self-employed workers have fluctuating income and a different set of financial documentation requirements. Understanding how to navigate these complexities is crucial for self-employed individuals looking to buy a home.
First, it is important to recognize the documentation that lenders typically require. Self-employed borrowers often need to provide more paperwork compared to salaried employees. This may include tax returns for the past two years, profit and loss statements, and bank statements. Lenders want to see a consistent income history to ensure that you can afford your mortgage payments. Therefore, keeping meticulous financial records is essential. Organizing your documents ahead of time not only streamlines the process but also demonstrates to lenders your preparedness and reliability.
One common misconception is that self-employed individuals cannot qualify for a mortgage. This is far from the truth. Many lenders are eager to work with self-employed borrowers, but they need to assess your income differently. Your income might fluctuate from month to month, so lenders typically take an average of your income over a specific period. This method allows them to see the bigger picture of your financial situation.
It is also worth noting that lenders often look for stability in your business. They may want to know how long you have been self-employed and if your business is well-established. Generally, having at least two years of self-employment history can increase your chances of securing a mortgage. Be prepared to explain any gaps in employment or significant fluctuations in income. A well-prepared explanation can go a long way in alleviating a lender's concerns.
Credit score plays a critical role in the mortgage process. Self-employed individuals should pay close attention to their credit report and score. Lenders typically look for a credit score of 620 or higher, but better rates and terms can be secured with a score above 740. If your score is below this threshold, consider taking time to improve it before applying for a mortgage. This may involve paying down existing debts, making payments on time, and avoiding any new credit inquiries.
Another key factor is the debt-to-income (DTI) ratio, which compares your monthly debt payments to your gross monthly income. Lenders prefer a DTI ratio below 43%. However, if you are self-employed, lenders may have additional guidelines, so it is essential to understand how your unique situation may affect your DTI calculations. Working with a mortgage professional can help you better understand your ratio and how to manage it effectively.
Self-employed borrowers should also be aware of the types of mortgage programs available to them. Conventional loans, FHA loans, and VA loans all have different requirements that might suit your financial situation. Each program has its benefits and drawbacks, so consider what would work best for you. Keep in mind that some lenders may offer programs specifically designed for self-employed individuals, which can simplify the process and provide more lenient qualification criteria.
Another crucial element in securing a mortgage is the down payment. While conventional loans may require a down payment of 20%, other programs, such as FHA loans, allow for lower down payments. Self-employed individuals should assess their financial situation to determine how much they can comfortably afford. A larger down payment may enhance your chances of approval and can also result in better loan terms.
To further strengthen your application, consider obtaining a letter of explanation for any financial discrepancies or anomalies in your business income. This letter should clearly outline the reasons behind any significant changes in income and demonstrate your financial stability. Transparency is key, and providing context can help lenders feel more confident in your ability to repay the loan.
Networking can also play a significant role in the home-buying process. Building relationships with other self-employed individuals who have successfully secured mortgages can provide valuable insights and advice. They may share their experiences and offer tips on how to navigate any hurdles you may encounter along the way.
Lastly, remember that communication is vital. When you're ready to begin the mortgage process, consider reaching out to a knowledgeable mortgage professional who understands the intricacies of lending for self-employed individuals. They can help you assess your unique financial situation and create a tailored plan to ensure you meet your goals.
The journey to securing a mortgage as a self-employed individual may have its challenges, but with the right knowledge and preparation, it can also be a rewarding experience. Don’t hesitate to reach out to discuss your specific needs and how you can best position yourself in the market.