Mortgage Broker | NMLS: 235367
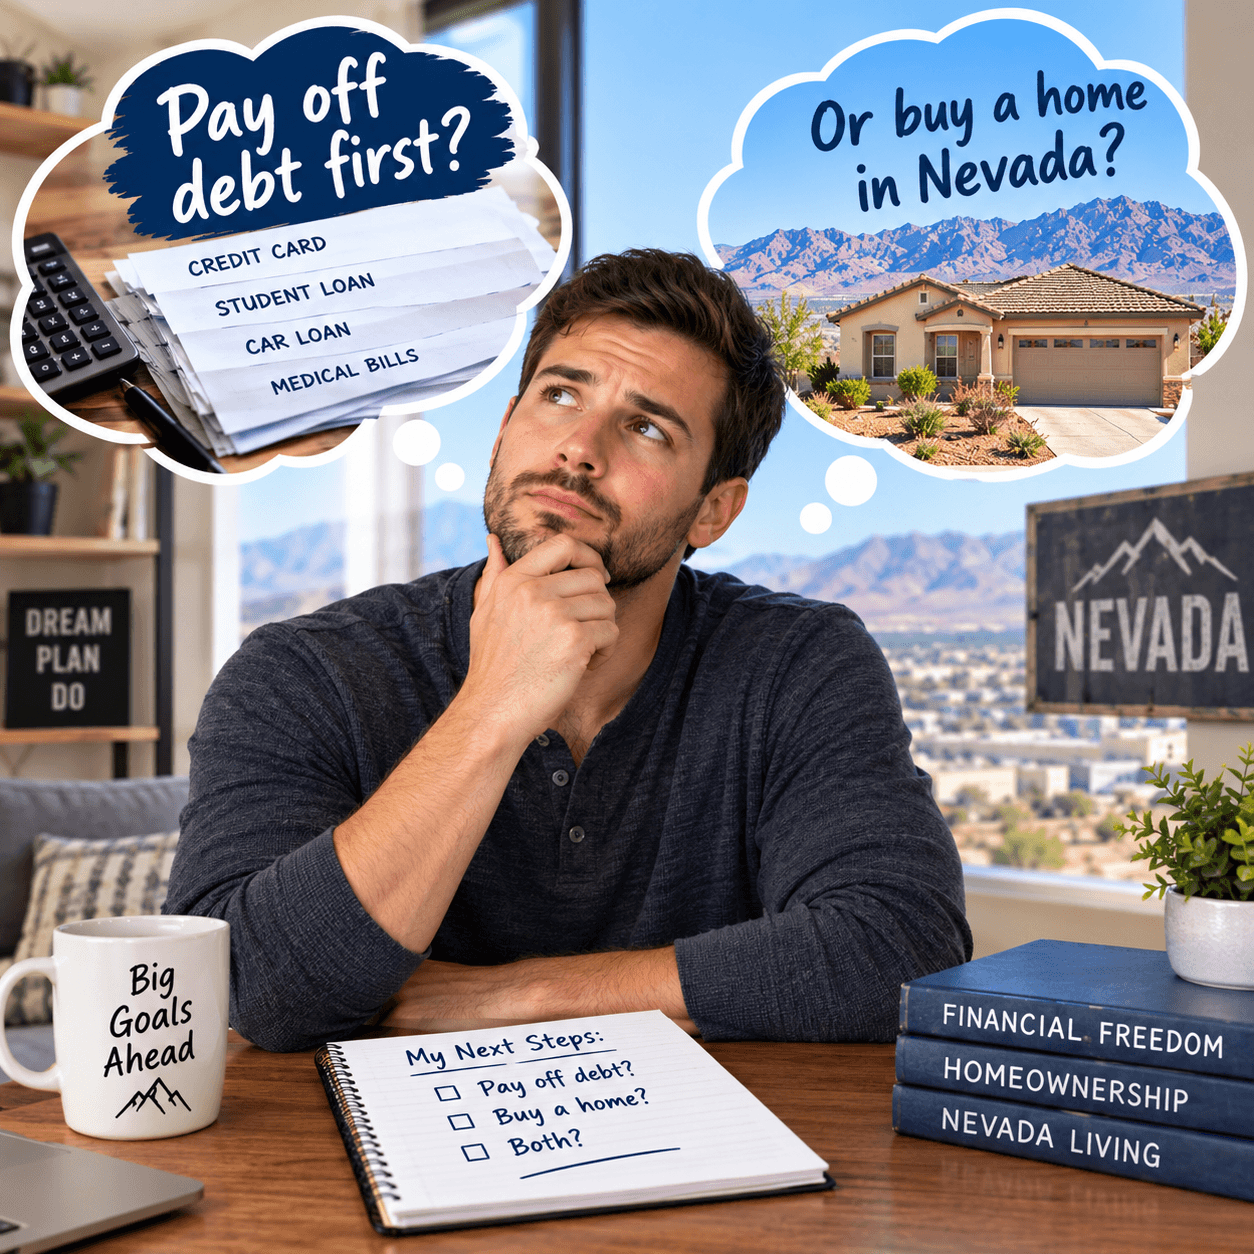
When considering the journey to homeownership, there’s a significant question that many potential buyers face: Should you focus on paying off existing debt before taking the leap into purchasing a home? This query is particularly relevant for those living in Nevada, where the real estate market can be both enticing and challenging. Understanding the balance between debt management and homeownership is crucial for making informed financial decisions that align with your long-term goals.
First, let’s delve into the nature of debt and its types. Many people carry different forms of debt, such as credit card debt, student loans, car loans, and personal loans. While some debts may seem manageable, others can pose challenges, particularly when you’re trying to qualify for a mortgage. Lenders evaluate your financial health through various metrics, one of which is your debt-to-income ratio (DTI). This ratio compares your monthly debt payments to your gross monthly income. Generally, a lower DTI is favorable as it indicates to lenders that you can handle additional debt, such as a mortgage.
If you currently have significant debt, it’s important to assess how this will impact your ability to secure a mortgage. Lenders usually prefer a DTI of 36% or less, although some may allow for higher ratios depending on other factors like credit score and financial reserves. Therefore, if your current debt is pushing you beyond this threshold, it may be wise to prioritize paying it down before pursuing a home purchase.
However, the decision isn’t simply about numbers. Emotional and psychological factors also play a significant role. Carrying debt can be stressful, and for some, the idea of adding a mortgage to existing obligations can be overwhelming. In contrast, others may feel ready to become homeowners and believe that investing in property would provide them with stability and potential equity growth. Weighing these emotional aspects is just as important as crunching the numbers.
In Nevada, the real estate market is diverse and dynamic. Places like Las Vegas and Reno often draw people looking to buy due to their vibrant communities and potential for investment growth. If you’re considering a home purchase in these areas but are also burdened with debt, you need to strategically evaluate your options. Sometimes, it might be beneficial to consult with a financial advisor who can help you map out a debt repayment plan while also considering how a home purchase fits into your larger financial picture.
Let’s examine a more nuanced perspective: the potential benefits of homeownership despite existing debt. Owning a home often comes with tax advantages and can serve as a long-term investment, building equity over time. If you believe that the property you’re looking at will appreciate in value, waiting to buy until all debts are paid off could mean losing out on valuable opportunities in a rising market. However, this doesn’t mean you should rush into a purchase without understanding your financial situation.
If you find yourself in a position where the desire to buy a home is strong, yet debt is a significant hurdle, consider a hybrid approach. Perhaps you can focus on paying down high-interest debts while simultaneously preparing for homeownership. For instance, creating a budget that allocates extra funds each month to reduce credit card balances can be a great start. At the same time, you can begin saving for a down payment and researching properties that fit your budget.
Another key aspect to consider is your credit score. Your credit score plays a critical role in the mortgage approval process. Higher credit scores can lead to better loan terms and interest rates, which can save you thousands over the life of the loan. If your credit score has taken a hit due to outstanding debts, prioritizing debt repayment could improve your score and, consequently, your mortgage options.
It’s also essential to stay updated on the various loan programs available. Some programs are designed specifically for first-time homebuyers, which may offer lower down payment requirements or more lenient DTI ratios. Researching these options might provide you with a pathway to homeownership that you hadn’t considered before.
Furthermore, as you navigate this decision, think about the stability of your job and income. If you’re in a secure position with steady employment, this may mitigate some of the risks associated with carrying debt while pursuing a mortgage. Lenders often look favorably upon consistent income as it suggests reliability in making monthly payments.
As you contemplate your options, keep in mind that every individual’s situation is unique. What works for one person may not work for another. Therefore, it’s crucial to take the time to assess your own financial landscape thoroughly. Factor in your current debt levels, your income, your credit score, and your personal feelings about debt and homeownership.
If you find yourself stuck between the decision of paying off debt or buying a home, a conversation with a mortgage professional can be incredibly beneficial. They can provide personalized advice tailored to your financial goals and help you outline the steps necessary to achieve them. Whether that means creating a debt repayment plan, exploring suitable mortgage options, or understanding how to balance both, having expert guidance can make all the difference.
In summary, the decision to prioritize paying off debt before purchasing a home in Nevada is multifaceted. It involves understanding not just the numbers, but also your emotional readiness and long-term financial goals. By taking a comprehensive approach and being open to discussions about your specific needs, you can navigate this debt dilemma more effectively. Reach out today to explore your options and take the next step toward your homeownership journey.
Mortgage Broker
Monica Vozza - Powered by Vision Home Mortgage | NMLS: 235367