Mortgage Broker | NMLS: 235367
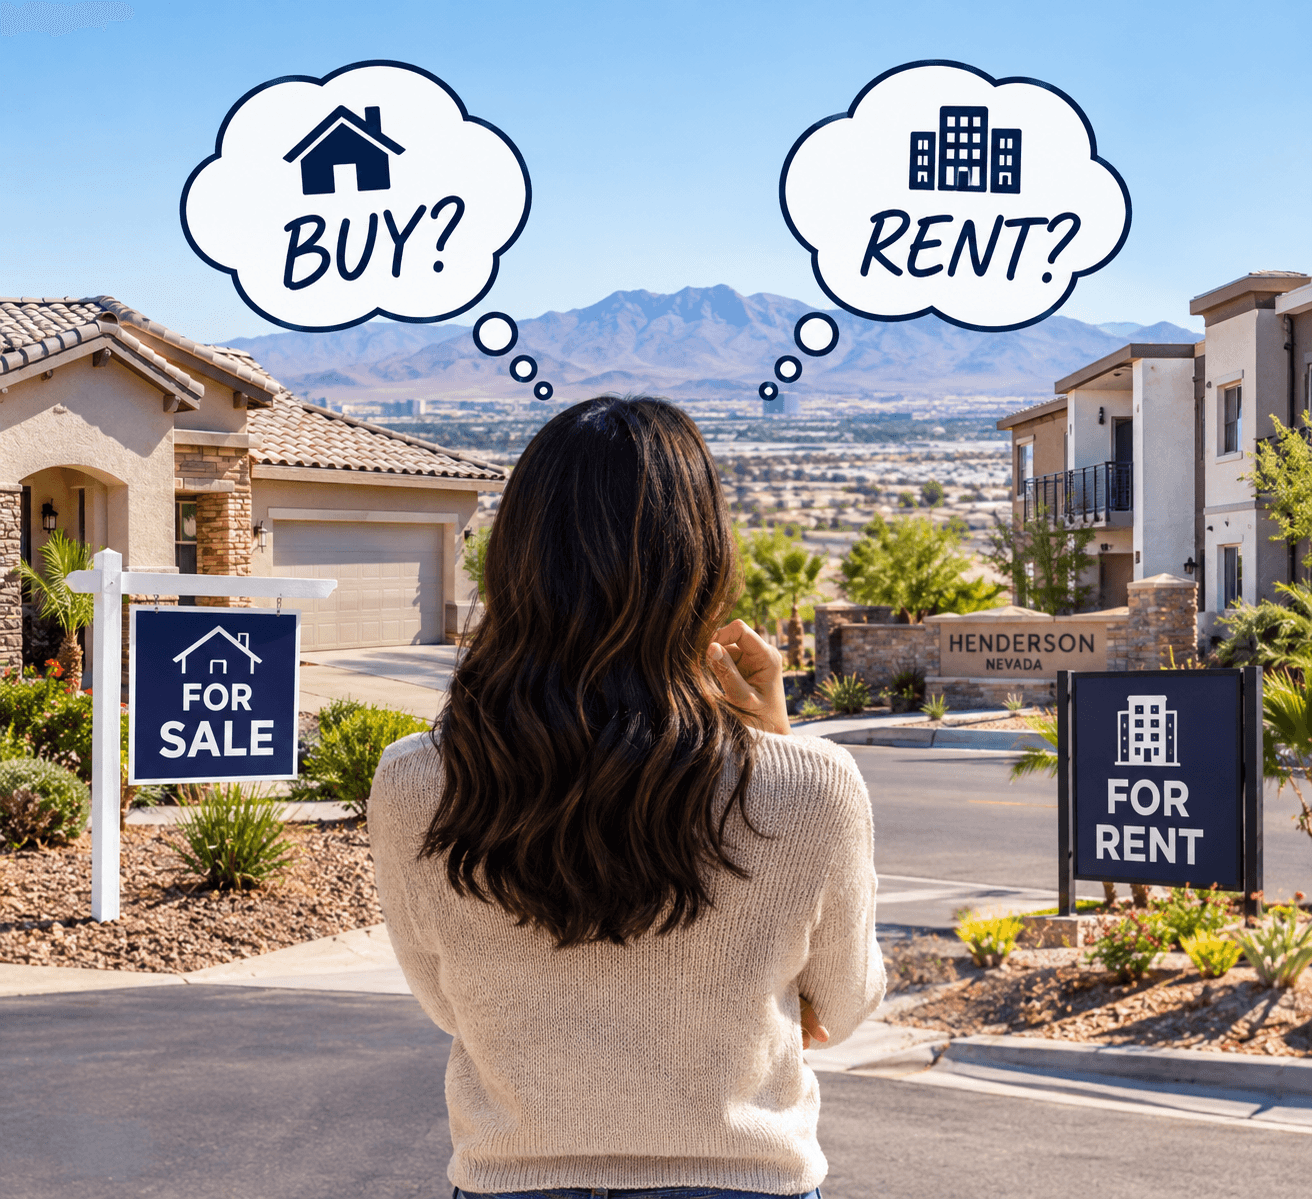
When it comes to living arrangements, the choice between buying a home and renting is one of the most significant decisions many people face. Each option comes with its own set of advantages and challenges, making it essential to understand your needs, preferences, and circumstances before making a choice.
To start, let’s examine the benefits of renting. One of the most appealing aspects of renting is flexibility. Renters can often move more easily than homeowners. If job opportunities arise in another city, or if your lifestyle changes, you can typically give notice and move on without the burden of selling a property. This flexibility is especially valuable for younger individuals or those in transitional life stages.
Renting also generally requires less upfront financial commitment. When you rent, you usually need to pay a security deposit and the first month’s rent. In contrast, buying a home comes with various costs, including the down payment, closing costs, and ongoing maintenance expenses. For many, the thought of these upfront costs can be daunting.
Another significant advantage of renting is that you are not responsible for the maintenance and repair of the property. If something breaks—like a water heater or a leaky roof—the landlord typically handles the repairs. This means that renters can enjoy their homes without worrying about unexpected repair bills.
However, renting does have its drawbacks. One major concern is the lack of equity building. When you rent, your monthly payments go to the landlord, and you don’t build any ownership in the property. For many, this means that they are missing out on the long-term financial benefits that come with owning a home.
Additionally, many renters face limitations when it comes to customizing their living space. Landlords often have strict policies on what modifications can be made to a rental unit. This can range from painting walls to adding shelves. For those who want to create a space that truly reflects their personality, this can be frustrating.
Now let’s consider the benefits of buying a home. One of the most significant advantages is the ability to build equity. Each mortgage payment represents an investment in your future. Over time, as you pay down your mortgage and as the property value increases, you can accumulate wealth that can be leveraged for future financial goals.
Homeownership also comes with potential tax benefits. Certain expenses related to owning a home, such as mortgage interest and property taxes, may be tax-deductible. This can provide significant savings for homeowners, which is an important consideration when evaluating your financial situation.
Another appealing aspect of homeownership is the freedom and flexibility to customize your living space. Homeowners can paint, renovate, and make improvements to their property without needing permission from a landlord. This ability to personalize your home can create a sense of pride and belonging.
However, owning a home is not without its challenges. Homebuyers face various upfront costs, including down payments and closing costs, which can be substantial. Additionally, homeowners are responsible for all maintenance and repairs, which can come with unexpected expenses that renters do not face.
Another factor to consider is the level of commitment associated with buying a home. Homeownership typically comes with a longer-term financial and personal commitment. If you anticipate moving within a few years or if your life circumstances are uncertain, it may be worth considering whether buying is the right choice for you.
When deciding between renting and buying, it’s crucial to evaluate your personal circumstances, financial situation, and long-term goals. Here are some steps to help guide your decision-making process:
1. Assess Your Financial Health: Take a close look at your financial situation. Calculate your monthly income, expenses, and savings. Factor in the costs associated with buying a home, including property taxes, homeowners insurance, and maintenance. This will give you a clearer picture of what you can afford.
2. Consider Your Lifestyle: Think about your current lifestyle and how it may change in the future. If you value flexibility and anticipate changes in your job or family situation, renting may be the more practical choice. On the other hand, if you’re looking for stability and a place to put down roots, homeownership might be the better option.
3. Research the Market: Whether you’re considering renting or buying, understanding the local real estate market is essential. Look at rental prices in your desired area and compare them to home prices. This will help you identify trends that can influence your decision.
4. Evaluate Your Long-Term Goals: Are you planning to start a family, or do you want to invest for the future? Understanding your long-term goals can significantly influence your choice. If you plan to stay in one place for several years, buying may make more sense.
5. Talk to a Professional: If you’re still unsure which path is right for you, consider reaching out to a mortgage professional. They can help you understand your options and provide tailored advice based on your specific needs and financial situation. This guidance can be invaluable in helping you make an informed decision.
6. Calculate the Total Cost of Ownership: If you decide to explore buying a home, be sure to understand all the costs involved. This includes not just the mortgage payments but also property taxes, insurance, maintenance, and potential homeowner association fees. Knowing the full picture will help you make a more informed decision.
7. Think About Future Financial Stability: Assess whether you have a stable income and job security. If you’re in a position to commit to a mortgage, it can be a wise investment over the long term. However, if your job situation is uncertain, renting may provide the flexibility you need.
Ultimately, the choice between buying and renting is a personal decision, influenced by your lifestyle, financial situation, and future aspirations. It’s essential to weigh the pros and cons of each option and how they align with your goals.
As you navigate this important decision, remember that you don’t have to do it alone. Reach out to discuss your specific needs and explore your options further. Together, we can find a path that aligns with your goals and provides you with the best home choice for your unique circumstances.
Mortgage Broker
Monica Vozza - Powered by Vision Home Mortgage | NMLS: 235367