Mortgage Broker | NMLS: 235367
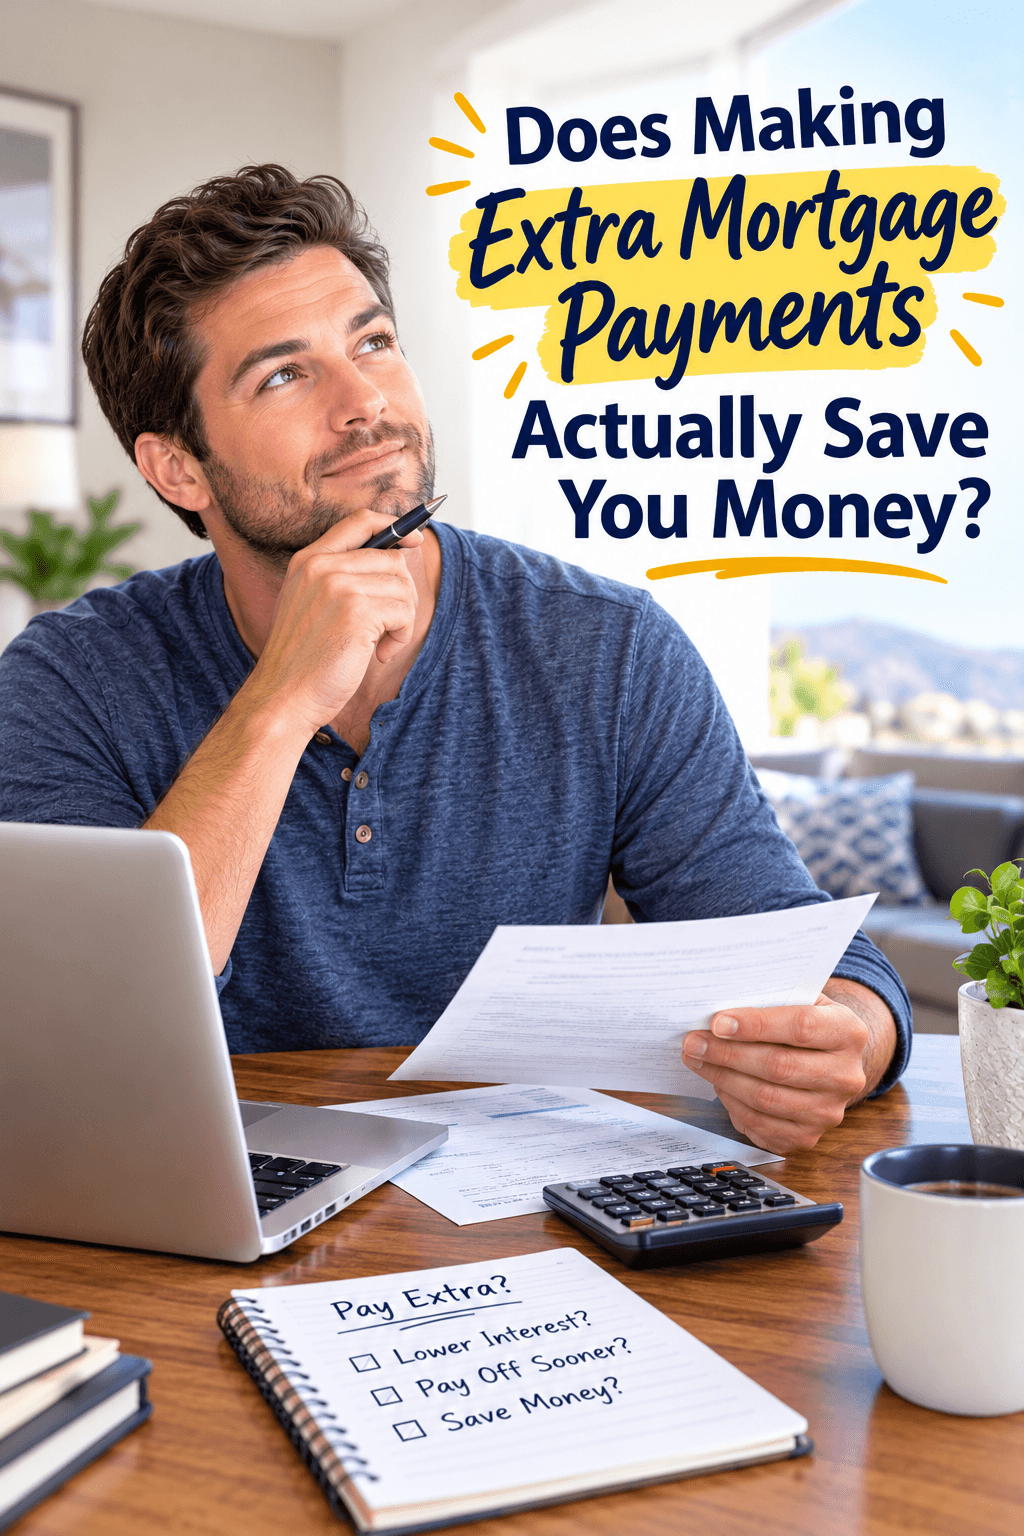
When it comes to managing a mortgage, many homeowners are interested in ways to reduce their overall costs. One effective method to achieve this is through making extra mortgage payments. This strategy can lead to substantial savings over the life of a loan. In this blog, I will explain how making additional payments works, the benefits it brings, and some suggestions to help you reach your financial goals.
First, let’s understand how a mortgage works. A mortgage is a loan taken out to purchase a home, and it is typically paid back over a period of 15 to 30 years. During this time, borrowers pay both principal and interest. The principal is the original amount borrowed, while interest is the cost of borrowing that money. Early on in the mortgage, a larger portion of your payment goes toward interest rather than paying down the principal. This is why making extra payments can be so beneficial.
When you make an extra mortgage payment, that additional money goes directly toward the principal. This reduces the amount of principal that remains on your loan. By lowering your principal balance, you also lower the total interest you’ll pay over the life of the loan. This is because interest is calculated based on the remaining balance of the mortgage. The less you owe, the less interest you will pay.
Let’s consider an example to illustrate this point. Suppose you have a $200,000 mortgage at a fixed interest rate. If you pay your regular monthly payment, a significant portion will go toward interest, especially in the early years. However, if you make an extra payment of $1,000 or add an extra $100 to each monthly payment, you can significantly shorten the time it takes to pay off your loan and reduce the total interest paid.
One of the most appealing aspects of making extra payments is the potential to save on interest costs. Over the life of a long-term mortgage, even small additional payments can lead to substantial savings. For instance, just adding an extra $100 a month could help save thousands of dollars in interest and reduce the term of your loan by several years.
It’s also important to note that when you make extra payments, you have the flexibility to do so at any time. You may choose to make extra payments when you have extra cash, such as tax refunds, bonuses from work, or gifts. This flexibility allows you to take control of your financial situation and can lead to greater peace of mind.
However, before you decide to make extra payments, consider your overall financial situation. It is wise to ensure that you have an emergency fund in place and that you are also contributing to retirement accounts or other savings goals. While paying down a mortgage is important, it’s crucial to balance that with other financial priorities.
If you are considering making extra payments, here are a few tips to help you get started:
1. **Check Your Loan Terms**: Before making any extra payments, review your mortgage terms. Some loans have prepayment penalties, which can negate the benefits of making extra payments. Understanding your loan’s terms will help you avoid unexpected fees.
2. **Set a Budget**: Determine how much extra you can afford to pay each month. A budget can help you identify areas where you can cut back on spending, allowing you to allocate more funds toward your mortgage.
3. **Make It Automatic**: Consider setting up automatic payments through your bank. This can help you consistently make extra payments without having to think about it each month. You can choose to make extra payments monthly, quarterly, or even annually.
4. **Target Specific Goals**: Decide what your goals are for making extra payments. Do you want to pay off your mortgage early? Or are you trying to save on interest? Having specific goals will help you stay motivated and focused.
5. **Track Your Progress**: Keep an eye on your mortgage balance and the interest you’re saving. This can be incredibly motivating. Seeing how much you’ve reduced your principal balance over time can encourage you to continue making extra payments.
6. **Consider Lump-Sum Payments**: If you receive a windfall, such as a bonus or an inheritance, consider applying that money directly to your mortgage principal. A lump-sum payment can make a significant impact on your loan balance and help you save on interest.
7. **Stay Informed**: The real estate market and mortgage industry can change. Staying informed about your mortgage and market trends can help you make better financial decisions.
8. **Communicate with Your Lender**: If you have questions about making extra payments or how it impacts your loan, reach out to your lender. They can provide guidance specific to your situation and help you understand the implications of your choices.
9. **Keep Long-Term Goals in Mind**: While focusing on reducing your mortgage is important, remember to keep your long-term financial goals in mind. Balance is key. Make sure you are still saving for retirement and other financial goals while paying down your mortgage.
Making extra mortgage payments can be an excellent strategy to reduce your overall costs and pay off your mortgage sooner. By understanding how this works, setting clear goals, and staying informed, you can take significant steps toward financial freedom. If you have specific questions or want to discuss your unique situation further, I encourage you to reach out to me. Together, we can explore how extra payments can help you meet your financial goals.
Monica Vozza
Mortgage Broker
Getting started is quick and easy
If you have any questions, I'm here for you.
Send Monica a message
I will get back to you soon.