Mortgage Broker | NMLS: 235367
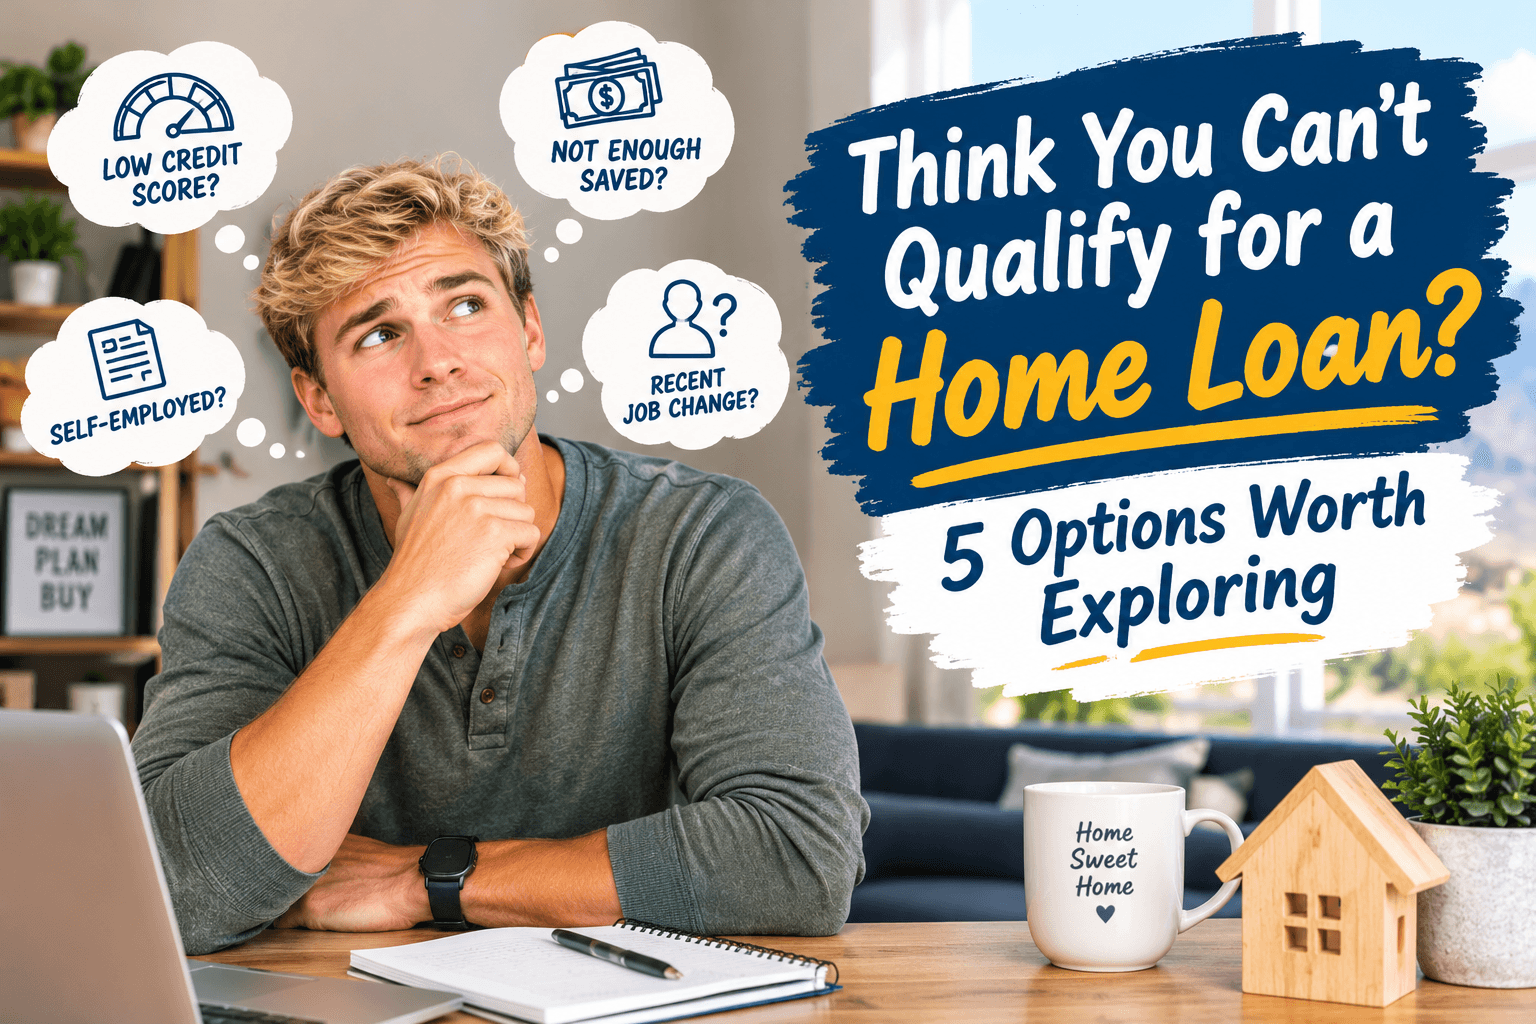
Buying a home can feel like a daunting task, especially when it comes to understanding your mortgage options. Many people worry that they won't qualify for a loan because of various factors such as credit score, income level, or their debt-to-income ratio. However, there are several mortgage options available that can help you navigate through these challenges and secure funding for your dream home. Here, we will explore five such options that cater to different situations and backgrounds.
First, let’s talk about FHA loans. The Federal Housing Administration (FHA) offers loans that are designed to help individuals and families with lower credit scores or those who may not have a large down payment saved. FHA loans typically require a down payment of just 3.5%, which makes them accessible for many first-time homebuyers. One of the best parts of an FHA loan is that it allows for a lower credit score than conventional loans. Even if you have had some financial challenges in the past, you might still be able to qualify. FHA loans also come with mortgage insurance premiums, which protects the lender in case of default. Understanding how the insurance works and factoring it into your budget is crucial as you consider this option.
Next, let’s look into VA loans. These loans are specifically designed for veterans and active-duty service members, as well as some members of the National Guard and Reserves. One of the most attractive features of VA loans is that they often do not require a down payment, making homeownership more attainable for eligible individuals. Additionally, VA loans usually have competitive interest rates and do not require private mortgage insurance (PMI). This can save you money in the long run. If you are a veteran or know someone who is, it’s essential to explore this option. Make sure to gather the necessary documentation to prove your eligibility, as this will streamline the application process.
Another option worth exploring is USDA loans. The U.S. Department of Agriculture (USDA) offers loans for rural and suburban homebuyers who meet certain income limits. These loans are designed to promote homeownership in areas that may not attract a lot of traditional lending. Like VA loans, USDA loans can offer 100% financing, which means no down payment is required. This is particularly beneficial for families who may struggle to save for a down payment. To qualify for a USDA loan, you will need to meet specific income eligibility requirements, which typically means that your income must be at or below 115% of the median income for your area. If you think you might qualify, it’s worthwhile to check out this option.
If you’re self-employed or have income that isn’t easy to verify, a bank statement loan could be a suitable choice. These loans allow you to use your bank statements instead of traditional documentation, such as W-2s and pay stubs, to prove your income. This could be a great fit for freelancers, contractors, or small business owners who may have fluctuating incomes. It’s important to note that while these loans can be more flexible, they may come with slightly higher interest rates and fees because of the increased risk to lenders. Be sure to fully understand the terms and conditions if you consider this route.
Lastly, let’s discuss conventional loans. These are the most common types of mortgages and are not backed by the government. Conventional loans come with various options, including fixed-rate and adjustable-rate mortgages. With a conventional loan, the minimum down payment is typically 3%, depending on the lender and your financial situation. While conventional loans often require a higher credit score than FHA or VA loans, they can be a good fit for those who have built a strong credit profile. Keep in mind that if your down payment is less than 20%, you may have to pay for PMI.
As you explore these five mortgage options, it’s essential to communicate openly with your mortgage loan officer. Share your financial situation and any concerns you have about qualifying for a loan. Each person's circumstances are unique, and it’s crucial to find a mortgage solution that fits your needs.
Additionally, gathering your financial documents will help you better understand your position. This includes your credit report, income statements, and any debts you may have. Being prepared can help streamline the loan process and make it easier for you to find the right mortgage option.
Consider setting goals for your homeownership journey. Think about what you want in a home and how much you can afford to pay each month. This will help guide your conversations with your mortgage loan officer and ensure you're both on the same page.
In summary, although qualifying for a mortgage might seem tough, there are various options available to help you achieve your homeownership dreams. Whether you are a veteran, live in a rural area, or are self-employed, there are programs designed to assist you. Each mortgage type has its own benefits and requirements, so it’s vital to assess your situation carefully.
If you’re ready to take the next step or if you have any questions about your mortgage options, reach out today. Understanding your choices can make a significant difference in your journey towards homeownership.
Monica Vozza
Mortgage Broker
Getting started is quick and easy
If you have any questions, I'm here for you.
Send Monica a message
I will get back to you soon.